All Categories
Featured
Core Financial Literacy Concepts for Adults in 2026

Building Stronger Financial Literacy Skills for Life

Ways to Fix Your Credit Fast in 2026
Table of Contents
Closing credit cards to "begin fresh"Overlooking balances and hoping scores repair themselvesApplying for numerous brand-new accounts to balance out debtThese relocations usually slow recovery rather of assisting it. If you're not exactly sure where to start, you do not need to figure it out alone. Langley offers tools and resources to support healthier credit routines, consisting of: to help keep payments on timeSavings-building tools like the Educational covering credit, financial obligation, and financial essentials Holiday costs does not specify your financial future.
Budgeting and Financial Counseling StrategiesHoliday spending often affects credit rating through greater balances or missed payments Many credit history drops are temporary Paying down balances and remaining consistent assists scores rebound Tools like Langley's Credit Builder Loan can support long-term healing.
Excellent credit can make it easier to do anything from lease a home to receive a lower rate on an auto loan. On the other hand, bad credit can be a barrier to accomplishing your objectives. When your credit rating is a barrier to the monetary life you want, companies assuring credit repair work might appear like rescuers.
Essential Financial Literacy for Adults in 2026
Credit repair business often charge substantial costs to discover and dispute negative information on your credit reports. The good news is you do not have to pay any person to repair your credit. You can fix your credit totally free by checking your credit report and taking steps to enhance your credit report.
Mistakes in credit reports are uncommon however might appear from time to time, and depending on the information included, might negatively affect your credit rating. Examining your credit report from each of the three major credit bureaus (Experian, TransUnion and Equifax) a minimum of when a year assists you spot problems.
Review your credit report for the following: Open credit accounts and accounts closed for approximately 10 years appear on your credit report. Try to find accounts you don't acknowledge, payments improperly reported as late and other prospective mistakes. This includes your name and any variations, birth date, and present and past addresses and companies.

Difficult questions happen when you look for credit; a difficult query you do not acknowledge might indicate fraud. Unreliable negative info, even if it's just a late payment that was really paid on time, could lower your credit report. Mistakes in personal information, such a name or address reported improperly by a lender, won't impact your credit rating however must still be fixed.
Once you file a disagreement, Experian asks the company that offered the disputed information to inspect their records. Incorrect info will be corrected; info that can't be verified will be erased or updated.
Locating Free Financial Counseling in 2026
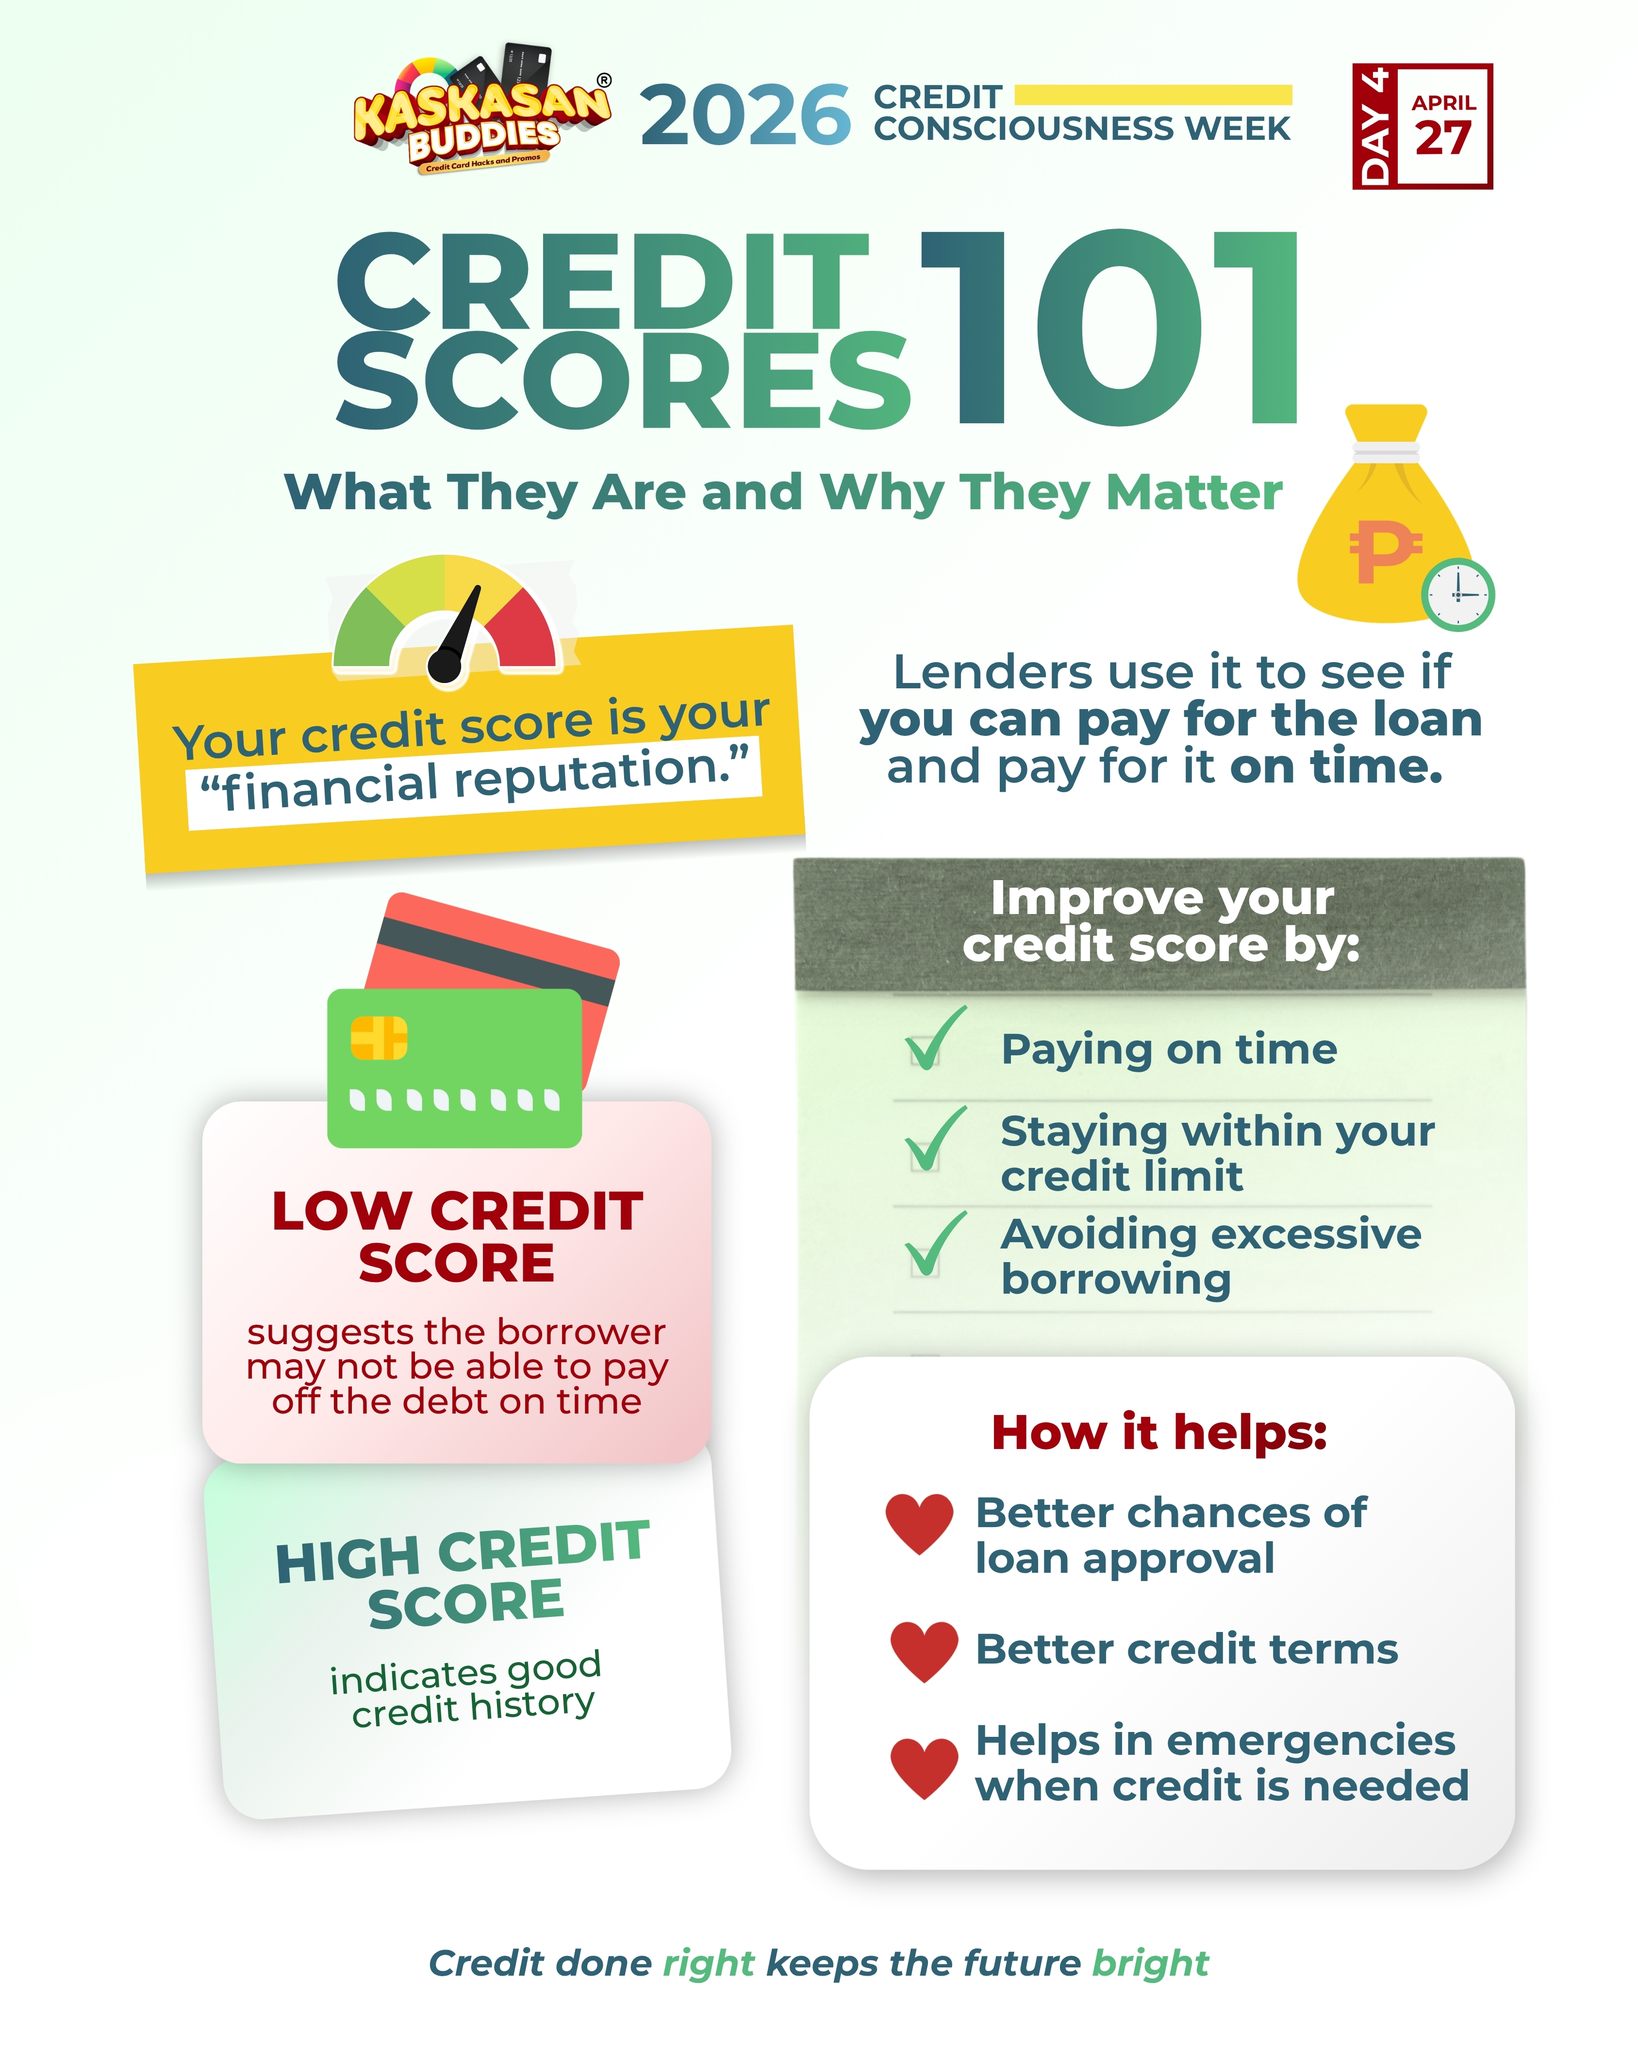
Due to the fact that payment history is the greatest element in your credit score, even one late payment can reduce your rating. If you're late however not yet 30 days behind on a payment, pay it immediately.
Can't afford to make the payment? Contact the loan provider to ask about difficulty options. Payment history represent 35% of your FICO Rating, so once your accounts are all existing, keep them that method by establishing autopay. You can normally set up autopay directly with the lender or provider or through the bank account you utilize to pay costs.
Ideally, though, you ought to pay the balance in complete every month. Credit utilization accounts for up to 30% of your credit rating.
A Guide to Improving Credit in 2026
Do this for each card you hold and for the total of all your credit cards. If your usage rate is 30% or more general or on a single account, pay for your credit card balances to see a potential increase to your credit history. The lower your credit usage, the better.
We'll detect bills with on-time payments, and you can include them to your Experian credit file. You'll find out right away if your credit scores increased and by how numerous points. Not only is high-interest financial obligation costly, but the quantity of financial obligation you carry has an effect on your rating.

Latest Posts
Building Credit Through Advanced Financial Literacy Education

Core Financial Literacy Concepts for Adults in 2026
A Guide to Improving Credit in 2026